A network portal of Wine Idea. Discover the world of Wine idea

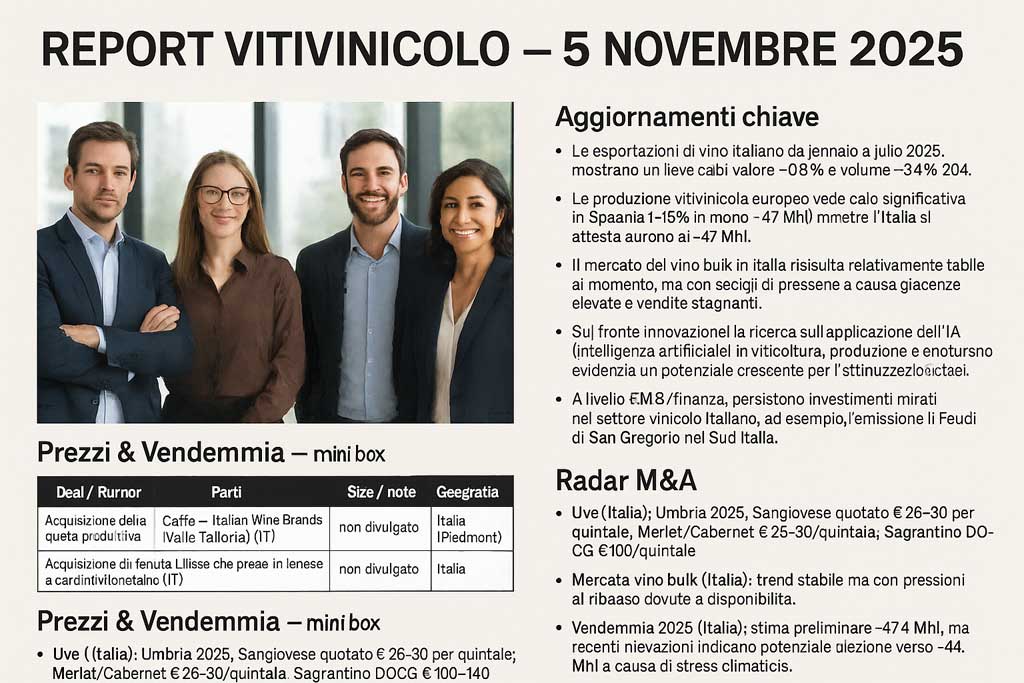
Wine Report of November 5 2025

Current trends in Italian and world wine.

Key updates

  • Italian wine exports from January to July 2025 show a slight decline: value -0.9% and volume -3.4% compared to the same period in 2024.
  • European wine production saw a significant decline in Spain (~15% less, ~31.5 Mhl) while Italy stood at around ~47 Mhl and France at ~37 Mhl.
  • The bulk wine market in Italy is currently relatively stable, but with signs of pressure due to high inventories and stagnant sales.
  • On the innovation front: Research into the application of AI (artificial intelligence) in viticulture, production, and wine tourism highlights growing potential for cost optimization and sustainability.
  • At consumer level, Italy has seen a very modest increase in wine prices over the last 10 years (7.4%), a sign of initial “resistance” from the medium-high segments of the sector.
  • Under M&A/finance, targeted investments in the Italian wine sector persist: for example, the bond issue by Feudi di San Gregorio in Southern Italy.
  • In the export channel, the USA is becoming a source of concern (tariffs, accumulations), and the need to diversify towards new markets with medium-long term strategic planning is essential.

M&A Radar

Deal / RumorPartsSize / noteGeographySource
Acquisition of the production share of Italian Wine Brands (Valle Talloria) by Gruppo Caffo 1915 (IT)Caffo ↔ Italian Wine Brandsnot disclosedItaly (Piedmont)
Acquisition of Tenuta Ulisse, which takes over management of the Montevetrano winery (IT)Tenuta Ulisse (investment firm) ↔ Montevetranonot disclosed

Prices & Harvest – mini box

  • Grapes (Italy) : Umbria 2025, Sangiovese priced at €26-30 per quintal; Merlot/Cabernet €28-30/quintal; Sagrantino DOCG €100-140/quintal.
  • Bulk wine market (Italy) : stable trend but with downward pressure due to high availability.
  • Harvest 2025 (Italy) : preliminary estimate ~47.4 Mhl, but recent findings indicate a potential reduction towards ~44 Mhl due to climatic stress.

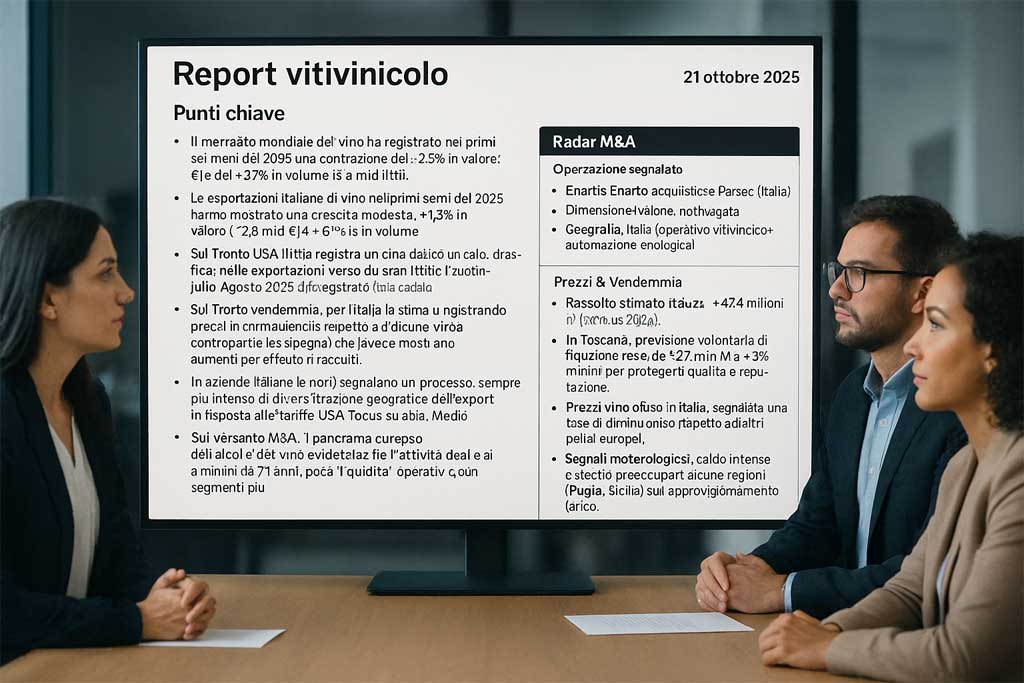
Wine Report of October 21, 2025

on the main news in the world of wine and wineries, with a strategic eye for those working in the sector.

Key points

  • In the first six months of 2025, the global wine market recorded a contraction of -2.3% in value (€16.7 billion) and -3.7% in volume (4.6 billion litres).
  • Italian wine exports in the first six months of 2025 showed modest growth: 1.5% in value (≈ €2.8 billion) and 2.1% in volume (≈703.5 million litres).
  • However, for the US market, Italy is recording a drastic decline: exports to the United States in July-August 2025 recorded a drop of -28% in value , despite average price cuts.
  • On the harvest front: for Italy the 2025 estimate is around 47.4 million hl (≈ 8% compared to 2024), returning to a world production record.
  • In the bulk wine market, Italy is seeing decreasing prices compared to some counterparts (e.g. Spain) which are instead showing increases due to reduced harvests.
  • Italian (and non-Italian) companies are reporting an increasingly intense process of geographical diversification of exports in response to US tariffs: focus on Asia, the Middle East, and South America.
  • On the M&A front, the European alcohol and wine landscape shows that deal activity is at a 27-year low: low operating liquidity, more active premium segments.

M&A Radar

Operation reported

  • Shares : Enartis acquires Parsec (Italy)
  • Size/Value : Not disclosed
  • Geography : Italy (winemaking and winemaking automation operations)
  • Strategic angle : fusion between winemaking solutions and automation / process control, a sign of vertical integration and tech upgrade in the winery sector.

Prices & Harvest

  • Estimated harvest Italy 2025: ~47.4 million hl (8% vs 2024).
  • In Tuscany, a voluntary reduction in yields is forecast: from ~2.7 million hl to ~2.4 million hl to protect quality and reputation.
  • Bulk wine prices in Italy have been reported to be decreasing compared to other European countries.
  • Weather signals: intense heat and drought are causing concern in some regions (Puglia, Sicily) regarding water supplies.

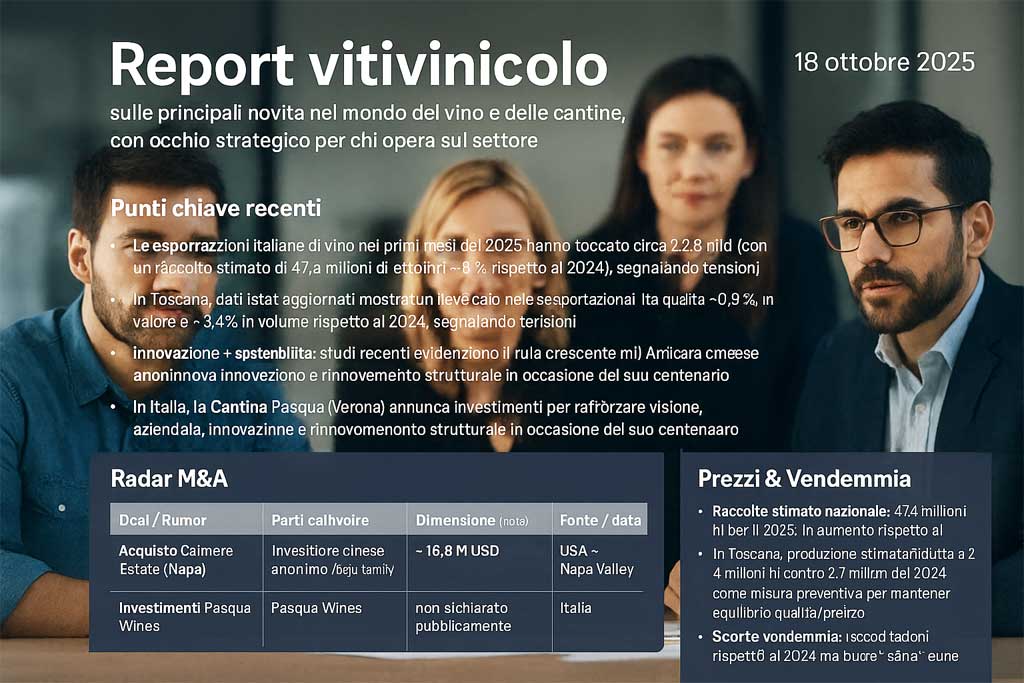
Wine Report of October 18, 2025

on the main news in the world of wine and wineries, with a strategic eye for those working in the sector.

Recent Key Points

  • Italian wine exports in the first months of 2025 reached approximately €2.8 billion (with an estimated harvest of 47.4 million hectoliters, 8% compared to 2024)
  • However, updated Istat data show a slight drop in Italian exports in July: -0.9% in value and -3.4% in volume compared to 2024, signalling tensions (also linked to US tariffs)
  • In Tuscany, a voluntary reduction in yields is expected for 2025: from 2.7 to 2.4 million hl, with the aim of protecting quality, reputation and prices.
  • Italian vineyards report a slight delay in the harvest (5-7 days compared to 2024) but good general conditions of the fruit, promising quality and the absence of widespread emergencies
  • Sustainability innovation: Recent studies highlight the growing role of AI applied to viticulture, production, and wine tourism as a driver of efficiency, forecasting, resource savings, and experience personalization.
  • On the M&A front, the recent cash purchase of the Calmére winery (Napa, USA) for $16.8 million by an anonymous Chinese investor, with plans to expand and build brands aimed at Asian markets.
  • In Italy, Cantina Pasqua (Verona) announces investments to strengthen corporate vision, innovation and structural renewal on the occasion of its centenary

M&A Radar

Deal / RumorParties involvedSize (public note)GeographySource / date
Purchase Calmére Estate (Napa)Anonymous Chinese investor / Peju family~ 16.8 M USDUSA – Napa Valley
Pasqua Wines InvestmentsPasqua Wines (Italian company)not publicly statedItaly (Veron

Prices & Harvest (mini box)

  • Estimated national harvest: 47.4 million hl for 2025, up from last year.
  • In Tuscany: estimated production reduced to 2.4 million hl from 2.7 million in 2024, as a preventive measure to maintain quality/price balance.
  • Harvest trend: slightly later harvest (5-7 days) compared to 2024 but with “healthy” grapes and good general conditions
  • Stocks: as of July 31, 2025, there are approximately 39.8 million hl in registered stock, which will be added to the 2025 production
  • Bulk grape/wine prices: no reliable updated national values (or broken down by variety/region) emerge from recent sources — the focus today is predominantly on quality and positioning dynamics.
  • Weather/Yield observation: No phytosanitary emergencies have been detected nationwide; some areas have been monitored for water stress and phenological delays, but so far without significant structural losses.

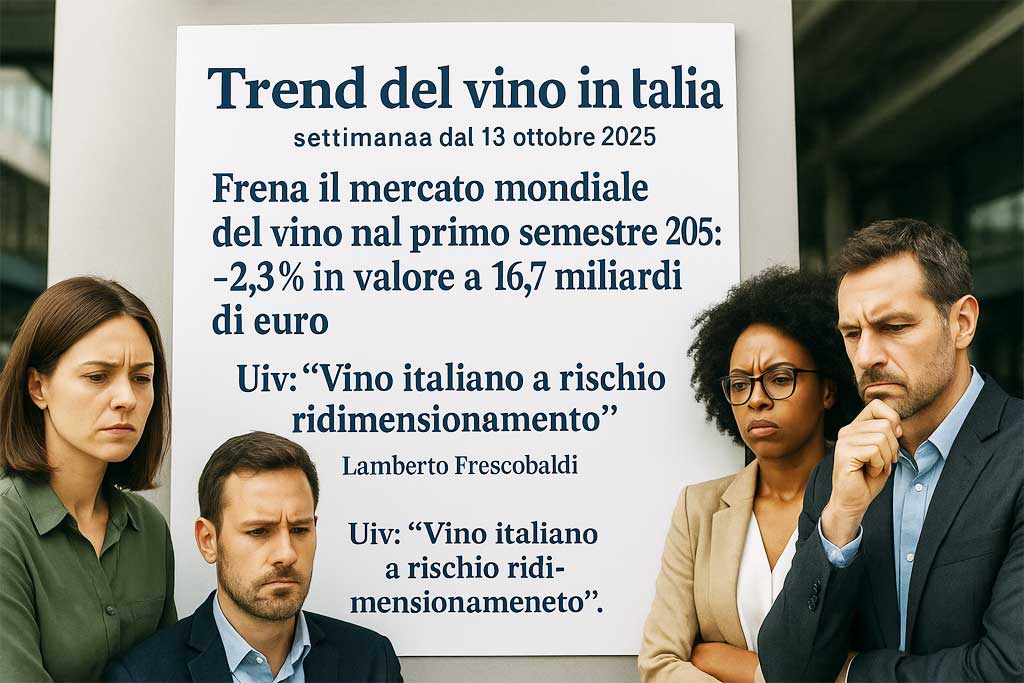
Wine Trends in Italy — Week 13–17 October 2025

Executive summary.

The first half of 2025 closed with a slowdown in world wine trade (-2.3% in value, 16.7 billion ¤, -3.7% in volume, 4.6 billion L; average price 3.57 ¤/L).

The slowdown is across all categories, with sparkling wines almost stable and bottled wines leading the decline. The US remains the primary import market, but 15% tariffs and a weak dollar are squeezing Italian producers’ margins, which in many cases are absorbing the tariffs through price reductions. In Italy, inventories remain high (36 million hl as of September 30) and domestic demand is polarized: large-scale retail trade is slightly growing in value but declining in volume; out-of-home consumption is “less but better.” UIV is supporting a financial promotion booster . On the financial front, banking and supply chain transactions confirm the credit focus on the sector.

Key numbers of the week

  • World trade 1H 2025: value -2.3% (€16.7 billion) | volume -3.7% (€4.6 billion) | average price €0.06/L to €3.57/L.
  • Categories:
    • Bottled: €11.3 billion (-3.1%) , 2.3 billion L (-4.8%).
    • Sparkling wines: €3.72 billion (-0.3%) , 479 million L (-0.4%).
    • Bulk: €1.2 billion (-0.4%) , L1.6 billion (-2.4%).
    • Bag-in-box: €345 million (-1%) , L175 million (-5.3%).
  • Top importers by value (1H 2025): USA €3.2 billion (6.5%) ; UK €1.98 billion (-5.4%) ; Germany ~ €1.3 billion (6.9%) ; followed by Canada, Japan (4.3%, driven by sparkling wines 14.6%), the Netherlands, China, Switzerland (5.8%), Belgium (3.4%), Sweden (above France).
  • Top importers by volume: Germany 647.9 million L (-1.1%) ; USA 645.4 million L (1.9%) ; UK 551.9 million L (-6.4%) ; Italy 129.2 million L (-28.5%) in imports.
  • USA in 2025: 30.8% in January, 20.2% in February, 14.7% in March; then -1.5% in April, -16.8% in May, -3.1% in June in value (but 3.8% in volume).
  • Russia: sharp drops in bottled wines (-37.1% in volume) and sparkling wines (-25.7% in value 1H 2025).
  • Italy – stocks: 36 million hl of wine as of 09/30/2025 (-9.6% vs July; 1.3% vs September 2024) 8.5 million hl of must 4.6 million hl VNAIF.
  • Italy – Large-scale retail trade (August 2025): €3.1 billion (0.6% value; -1.8% volume). Sparkling wines in large-scale retail trade: €784 million (1% value; 2.2% volume). Still DOP wines: -3.4% volume (stable value) ; IGP wines: -1.7% volume, 1.2% value.
  • Out of home: 9 out of 10 Italians have frequented bars in the last three months; by 2026, 19% will reduce their outings, but 66% are aiming for higher-value experiences . No/low-alcohol niches are growing.
  • US tariffs: estimated cost of €61 million for Italy in the first few months; average price of Italian wine in the US in July 2025: -13.5% , tariff absorption strategy (not sustainable for everyone).
  • 2025 harvest: a qualitatively excellent and abundant vintage (~ 47.4 million hl , 8% vs. 2024; alternative estimates 44–45 million hl). Previous inventories of ~37 million hl to be disposed of.
  • Finance & Supply Chain:
    • Piccini 1882: €36 million financing (Intesa, MPS, CDP) for international expansion and AI.
    • Terre Cevico–UniCredit: supply chain agreement for investments, exports, and ESG transition.

Strategic Reading (Italy)

  1. Margin compression on US exports
    Absorbing the tariff supports volumes but pushes towards down-pricing and the risk of de-premiumization if not accompanied by more selective storytelling and trade-marketing.
  2. Polarized domestic demand
    In large-scale retail, “value up, volume down”; in the out-of-home retail sector, selective premiumization . It’s appropriate to push premium formats/labels and experiences (wine tourism, wine pairing, by the glass).
  3. High stocks, abundant harvest
    Necessary disposal plan : portfolio management (blends, opportunity channels, technical distillation), focus on sparkling wines (more resilient segment) and non-US exports (Brazil, Mexico, selective Asia).
  4. Institutional promotion
    The booster promoted by UIV and the Government must be translated into coordinated campaigns in the USA and promising markets, with clear KPIs (ROS trade, rotation speed, weighted distribution).

Recommended actions for Italian wineries (Q4 2025 → H1 2026)

  • Protect the mix in the US: segment by country/retailer, favor channels with greater quality-price elasticity; review net price lists and promotions, avoiding linear discounts.
  • Promote sparkling wines and premium experiential wines in large-scale retail and hospitality sectors: party bundles, special formats, and limited editions.
  • Market diversification : focus on Brazil/Mexico ; ride sparkling wine trends in Japan ; and cautious tactics (slow rotations) in the UK .
  • Inventories : Technical distillation plans and selective private labels to free up space without eroding brands.
  • Domestic communication : support domestic demand with educational campaigns (moderation, quality, territory) and in-cellar experiences .
  • Finance : Evaluate working capital instruments and credit insurance ; leverage banking partnerships for exports and ESG.
Style Selector
Select the layout
Choose the theme
Preset colors
No Preset
Select the pattern