Investing in Wine in 2026: The Market Is Slowing, but the Best Opportunities May Be Emerging Now
Vineyards, wineries and wine estates: the data reveals an increasingly selective market. Prosecco, Asti, Piedmont and selected appellations are proving more resilient, while prices and valuations are becoming more rational.
Does investing in an Italian winery or wine estate still make sense in 2026?
The answer cannot be based simply on sales figures from a single quarter or year.
To understand what is really happening in the Italian wine industry, investors need to distinguish between three different dynamics:
short-term sales performance → structural changes in consumption → the underlying asset and industrial value of wine businesses.
Looking at these three dimensions together reveals a much more interesting scenario for investors.
The wine market is slowing.
But not every wine category is slowing at the same pace.
More importantly:
a slowing market does not necessarily mean a market in which investors should stop investing.
In some circumstances, it may mean exactly the opposite.
First Rule: Do Not Confuse the 2026 Slowdown with a Crisis in Italian Wine
To analyse the market properly, we need to take a longer-term perspective.
The years 2020–2022 were heavily influenced by the pandemic: restaurant closures, rapid e-commerce growth, changes in domestic consumption, logistics disruptions and the subsequent rebound in demand.
For this reason, 2019 remains a particularly useful benchmark for understanding the industry’s structural evolution.
This does not, however, mean ignoring what is happening today.
The latest figures clearly indicate a slowdown.
In 2025, global wine exports declined by approximately 6.7% in value.
Italy performed comparatively better, limiting the decline to around 3.7%, while remaining one of the world’s leading wine-producing and exporting countries.
This is important because it shows that the challenge is not exclusively Italian.
The global wine market itself is changing.
2026 Confirms the Slowdown: Italian PDO Wine Exports Down 6.2%
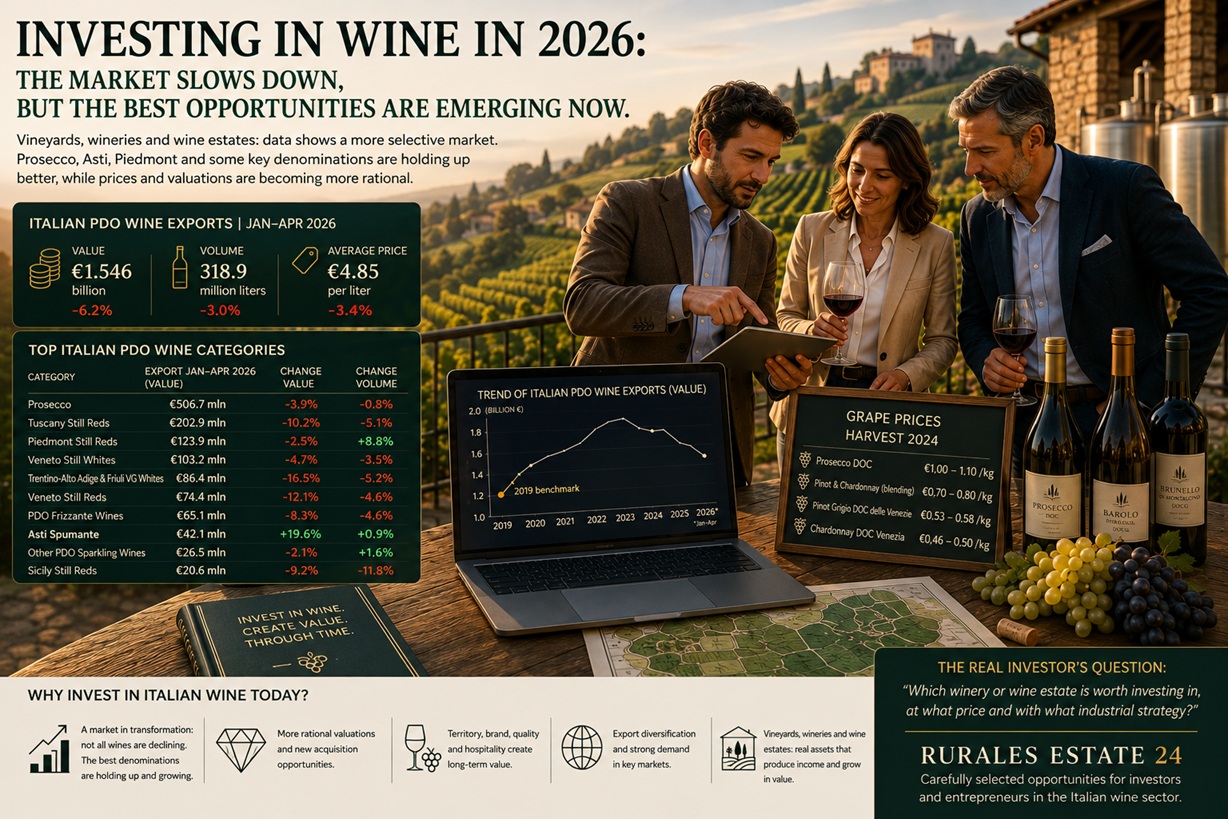
Nomisma Wine Monitor data for Italian PDO wine exports during the first four months of 2026 provides a clear picture of current market conditions.
Exports reached approximately:
€1.546 billion in value
representing a decline of:
-6.2% in value
and:
-3.0% in volume.
The average price fell by 3.4% to approximately €4.85 per litre.
These figures should not be underestimated.
But they need to be interpreted correctly.
Behind the national average are significantly different performances across wine categories and regions.
The Real Story: Not Every Wine Category Is Declining
This is perhaps the most important message for anyone considering an investment in the sector.
Looking at Italy’s main PDO wine categories reveals what could be described as a map of an increasingly selective market.
| Category | Exports Jan–Apr 2026 | Change in Value | Change in Volume |
|---|---|---|---|
| Prosecco | €506.7m | -3.9% | -0.8% |
| Tuscan still red wines | €202.9m | -10.2% | -5.1% |
| Piedmont still red wines | €123.9m | -2.5% | +8.8% |
| Veneto still white wines | €103.2m | -4.7% | -3.5% |
| Trentino-Alto Adige + Friuli-Venezia Giulia whites | €86.4m | -16.5% | -5.2% |
| Veneto still red wines | €74.4m | -12.1% | -4.6% |
| PDO semi-sparkling wines | €65.1m | -8.3% | -4.6% |
| Asti Spumante | €42.1m | +19.6% | +0.9% |
| Other PDO sparkling wines | €26.5m | -2.1% | +1.6% |
| Sicilian still red wines | €20.6m | -9.2% | -11.8% |
These figures tell us much more than the headline national decline of 6.2%.
They show that the market is becoming increasingly selective.
Prosecco: More Than Half a Billion Euros in Exports in Four Months
Prosecco remains by far the largest Italian PDO category analysed, generating approximately €506.7 million in exports during the first four months of 2026.
Export value declined by 3.9%, but volumes decreased by only 0.8%.
That difference matters.
It suggests that even in a difficult market, international demand for Prosecco continues to demonstrate considerable resilience.
For investors, this reinforces the strategic importance of businesses operating within:
Prosecco DOC and Conegliano Valdobbiadene Prosecco Superiore DOCG.
Naturally, valuations vary considerably depending on vineyard ownership, appellation, brand strength, distribution network and profitability.
This does not mean that every Prosecco winery automatically represents a good investment.
It means that territory, appellation and commercial strength continue to matter enormously.
Asti Spumante: +19.6%, One of the Surprises of 2026
One of the most striking performances is that of Asti Spumante.
During the first four months of 2026, exports reached:
€42.1 million
with:
+19.6% in value
and:
+0.9% in volume.
This is particularly interesting because it demonstrates that individual categories can move strongly against the overall market trend.
For investors, the lesson is clear:
do not simply invest “in wine”. Select the right appellation, territory, company and market positioning.
Piedmont: Lower Value, but Volumes Up 8.8%
Another figure worth examining closely concerns Piedmont still red wines.
Exports reached €123.9 million, with value declining by a relatively modest 2.5%.
However, volumes increased by 8.8%.
This deserves attention because territories such as Langhe, Barolo and Barbaresco combine several strategic characteristics:
- international reputation;
- limited vineyard availability;
- prestigious appellations;
- strong premium positioning;
- significant wine tourism appeal;
- an international fine-wine market.
In these areas, a vineyard is more than a productive agricultural asset.
It becomes part of the territory’s brand equity.
Tuscany: The Difference Between Wine Sales and Asset Value
Tuscan still red wines show a more significant decline:
€202.9 million in exports
-10.2% in value
-5.1% in volume.
However, it would be a mistake to conclude automatically that investing in Tuscany has become less attractive.
In territories such as:
Chianti Classico, Montalcino, Bolgheri and Montepulciano
an investment can combine multiple sources of value:
vineyards + wine + brand + real estate + landscape + hospitality + international tourism.
A Tuscan wine estate is not necessarily just a winery.
It can simultaneously be an agricultural business, a wine resort, a tourism destination, a real estate asset and a brand.
Its value therefore cannot be assessed solely on the basis of wine exports.
The European Comparison Helps Explain What Is Really Happening
The slowdown is not limited to Italy.
During the first four months of 2026, available data shows:
France: €2.816 billion, -3.4%
Italy: €1.547 billion, -6.2%
Spain: €435.1 million, -8.5%
Germany: €106.1 million, -5.5%
Portugal: €82.1 million, -0.6%
Spain also recorded an 11.4% decline in export volumes.
The European wine industry is therefore undergoing a structural transformation.
The key question is no longer simply:
“How much wine can we produce?”
The new question is:
“How much value can we create from every bottle, every customer and every hectare?”
From 2019 to 2026: Why Investors Need a Longer Perspective
Investors should never assess a winery solely on the basis of its latest financial statements.
2019 was the last full year before the pandemic.
Since then, the industry has experienced:
Covid → surge in domestic consumption → e-commerce growth → restaurant rebound → inflation → rising production costs → slowing consumption → geopolitical tensions → US tariffs → market normalisation.
Assessing a winery simply by comparing 2026 with 2024 or 2025 can therefore produce a distorted picture.
A serious due diligence process should reconstruct at least five to seven years of company history, distinguishing exceptional events from structural trends.
A Structural Challenge Remains: The World Is Drinking Less Wine
This reality should not be ignored.
According to Nomisma, declining consumption across major international markets is not simply the result of geopolitical uncertainty.
It is a trend that has been developing for more than a decade.
Consumer behaviour is changing in terms of:
- generations;
- drinking occasions;
- health awareness;
- frequency of consumption;
- competing beverage categories;
- purchasing behaviour.
Future growth in wine is therefore unlikely to be driven solely by increasing volumes.
For investors, this fundamentally changes the criteria used to select potential acquisitions.
The New Wine Equation: Less Volume, More Value
The traditional model was relatively straightforward:
produce → bottle → distribute → export.
The emerging model is considerably more sophisticated:
territory → quality → brand → pricing → distribution → direct sales → diversified exports → hospitality → wine tourism → direct consumer relationships.
This new model is precisely where many future investment opportunities may emerge.
Vineyard Valuations Are Becoming More Rational
Declining consumption and greater commercial selectivity are beginning to affect the vineyard market as well.
After years of significant price increases in some areas, several territories between 2025 and 2026 are showing signs of valuation normalisation.
Grape prices also provide useful indications.
For the 2024 harvest, indicative prices included:
- Prosecco DOC: €1.00–1.10/kg;
- Pinot and Chardonnay for blending: €0.70–0.80/kg;
- Pinot Grigio DOC delle Venezie: €0.53–0.58/kg;
- Chardonnay DOC Venezia: €0.46–0.50/kg.
Subsequent 2025 harvest data indicates a more selective market, with lower prices across several appellations.
Over time, this may also influence vineyard valuations.
And this is precisely where conditions may become particularly interesting for investors with available capital.
Why a Weaker Market Can Create Acquisition Opportunities
When everything is growing, buying well is difficult.
Owners have high expectations.
Valuations reflect optimism.
The best companies rarely come onto the market.
When an industry enters a period of transformation, however, new opportunities tend to emerge:
- generational succession situations;
- undercapitalised wineries;
- businesses with strong brands but weak distribution;
- quality vineyards at more rational valuations;
- family businesses without successors;
- estates with undeveloped wine-tourism potential;
- consolidation opportunities;
- strategic acquisitions by larger wine groups.
For an experienced investor, therefore, a slowdown does not necessarily represent a problem.
It may represent the moment when assets that were previously unavailable begin to come onto the market.
Do Not Buy Hectares. Buy the Ability to Create Value.
This should be one of the fundamental principles of wine investment in 2026.
Two wineries owning 20 hectares of vineyards may have completely different industrial values.
An investor should analyse:
1. Territory — Does the appellation have international recognition?
2. Vineyards — What are their productivity, age, exposure and market value?
3. Winery — Is production capacity appropriate or oversized?
4. Brand — Does the brand have history, reputation and growth potential?
5. Distribution — Where is the wine sold: Italy, USA, Germany, UK, Asia?
6. Profitability — How much does the company actually earn per bottle?
7. Inventory — What is the value and, more importantly, the turnover rate of wine stocks?
8. Hospitality — Are there buildings that could be developed into an agritourism business, wine resort, restaurant or event venue?
9. Direct-to-consumer sales — How much revenue is generated without intermediaries?
10. Management — Can the business grow after the acquisition?
The New Strategic Priority: Diversifying Export Markets
The United States remains crucial for Italian wine, but developments in 2025–2026 demonstrate the risks associated with excessive dependence on a limited number of markets.
According to the source text, Italian wine exports to 13 emerging markets monitored by Wine Monitor exceeded €400 million in 2025.
Australia, Mexico, Mercosur, India and other markets could gradually become more significant.
Germany also remains strategic: Italy accounts for more than 40% of the German imported wine market, representing more than €1 billion in value.
For a potential buyer, the geographical diversification of a winery’s customer base should therefore become an important component of its valuation.
Where Should Investors Look in the Italian Wine Market?
There is no universal ranking.
However, the data suggests paying particular attention to several types of assets and territories.
Prosecco DOC and Conegliano Valdobbiadene DOCG offer strong international recognition, a structured production system and significant export capacity.
Piedmont, particularly Langhe, Barolo and Barbaresco, combines scarcity, international reputation and premium positioning.
Tuscany, including Chianti Classico, Montalcino, Bolgheri and Montepulciano, provides the opportunity to integrate wine, real estate and hospitality.
Asti deserves attention following its strong sparkling-wine performance in 2026.
Sicily and Etna offer strong territorial differentiation and international potential.
Friuli-Venezia Giulia and Collio remain particularly interesting for premium white wines, despite challenging 2026 figures for some categories.
Marche, particularly areas associated with Verdicchio, may offer attractive value-creation opportunities.
Puglia continues to offer comparatively competitive land values in several areas alongside internationally recognised appellations.
What Kind of Wineries Should Investors Be Looking For?
The best opportunity is not necessarily the winery experiencing the strongest growth today.
Often, the most interesting target is the business where there is the greatest gap between current value and potential value.
For example:
excellent vineyards + weak brand
historic brand + insufficient exports
beautiful estate + no hospitality business
strong production + weak commercial organisation
family-owned winery + succession challenge
attractive wine business + need for growth capital
It is precisely within these imbalances that an industrial or strategic investor can create value.
Investing in Wine in 2026: Selection Is the Real Opportunity
Italian wine is not simply experiencing a crisis.
It is entering a more selective phase.
Global consumption is declining.
Exports are slowing.
Some appellations are under pressure.
Others are proving resilient.
Some are growing.
Vineyard valuations are becoming more rational.
More family businesses are facing succession challenges.
Wine tourism is creating additional revenue streams.
Larger and better-capitalised groups are looking for consolidation opportunities.
This combination could open a new phase of M&A activity in the Italian wine industry.
The Right Question Is Not: “Should I Invest in Wine?”
The right question is:
“Which winery or wine estate should I invest in, at what price, and with what industrial strategy?”
That distinction is fundamental.
Acquiring a winery today means evaluating simultaneously:
land + vineyards + buildings + production capacity + appellation + brand + customers + exports + hospitality + management + future potential.
A well-structured investment can therefore create value across three dimensions:
Asset Value
Land, vineyards, winery facilities and real estate.
Industrial Value
Production, efficiency, distribution and consolidation.
Commercial Value
Brand, exports, direct sales, hospitality and consumer relationships.
When these three dimensions come together, we are no longer simply talking about buying a winery.
We are talking about acquiring a value-creation platform within the Made in Italy economy.
Rurales Estate 24: Investing in Italian Wineries and Wine Estates
Rurales Estate 24 selects acquisition and investment opportunities across the Italian wine industry for wine groups, entrepreneurs, private investors, family offices and international buyers.
The objective is not simply to advertise wineries for sale.
It is to identify transactions where there is genuine potential to create additional value through:
acquisition, consolidation, commercial development, international expansion, brand development, wine tourism and hospitality.
Because in a more selective market, the winners will not necessarily be those who acquire the largest number of vineyards.
They will be those who acquire the right assets and know how to create more value from them.
For international investors, Rurales Estate 24 presents Italian wineries, vineyards and wine estates not simply as rural properties, but as integrated investment opportunities combining real estate with operating businesses.
Italy offers international investors a combination that is extremely difficult to replicate elsewhere:
vineyards + winery + appellation + brand + Made in Italy + hospitality + tourism + international distribution.
The current transformation of the wine market may bring businesses and estates onto the market that were difficult to acquire during years of stronger growth.
For this reason, 2026 should not be viewed solely as a year of slowdown.
It may also mark the beginning of a new phase of selective acquisition opportunities in the Italian wine industry.