The sector is in a “reorganization phase”: weak global demand for reds, US tariffs slowing purchases in Q2, inventories still high, but signs of stability in some markets (Canada, Germany, Japan, Brazil) and volume leadership confirmed in the USA.
Prosecco is the undisputed star. Domestically, consumer confidence is slightly up; more inclusive pricing policies are needed in the Ho.Re.Ca. channel to attract Gen Z and new wine consumers.
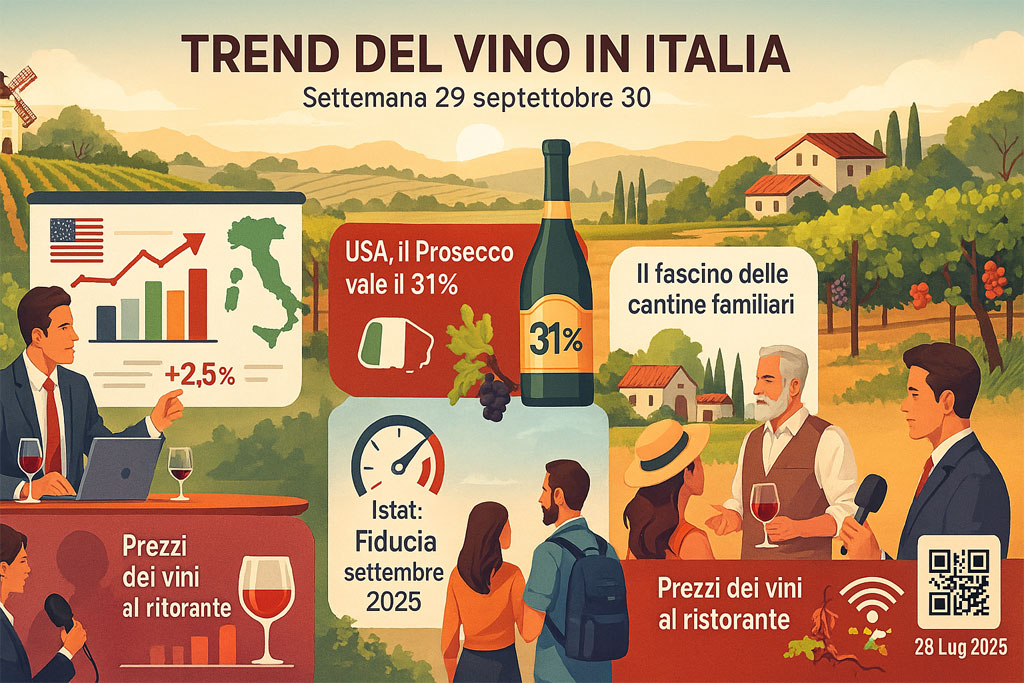
Wine Trends in Italy Week 29 September – 3 October 2025
Executive summary
Strategic priorities: export diversification, selective premium repositioning, inventory management, anti-counterfeiting traceability, and a push for data-driven “family” wine tourism.
Exports first semester 2025 (source Nomisma: monitored markets)
- USA : leading market but pre-tariff “pre-stocking” halted → from 22% (Jan–Mar) to -7% (Apr–Jun) . Italy: 2.5% in the first half thanks to Q1. Court of Appeals decision on legitimacy of tariffs pending.
- Canada : 11% imports from Italy; strong substitution of US wines on the shelves ( –65% ).
- Germany : 10.3% in value (still and sparkling goods: 14.2% ).
- Japan and Brazil : positive performances.
- United Kingdom : –7% in value ; sparkling wines –6.6% , still/sparkling wines –8.1% .
- Others in decline : Switzerland, South Korea, Norway, China ( -10.5% for still/sparkling wines).
- Italian sparkling wines (12 markets): growth slowed to 1% value / 6% vol ; dynamic Japan, USA, China . Weak UK, France, Australia .
Production, inventory and structure
- Supply chain: 30,000 processing companies (1,800 industrial), 250,000 agricultural; turnover €16 billion (excluding related industries), 2024 exports €8.1 billion , 74,000 employees.
- Italy: world’s leading producer (average 47 million hl ), leading exporter by volume ( >22 million hl ).
- Production volatility: peak 55 million hl (2018) ; minimum 38 million hl (2023) ; 2024 rising but below average; 2025 UIV estimate: 47.4 million hl ( 8% on 2024).
- Inventories : 2023 > production; July 2024: 40 million hl (–20% y/y with production –23%); 30 June 2025: 43.6 million hl (0.3% y/y; –6.4% on May), 2.7 million hl must and 63,926 hl new wine .
- Areas : Italy 728k ha (0.8%) ; national structural decline –15% (2000–2023) . EU27 3.2 million ha ; Spain 930k ha (–15%) , France 783k ha (–0.7%) ; China 753k ha (–0.4%) ; India growing 185k ha , CAGR 4.5% (from 2019) .
Prices, US tariffs and their impact
- Average export price (still in bottles): Italy €4.43/l , below France €7.81 , Australia €5.56 , New Zealand €5.86 .
- USA : worth ~ €2 billion (24% of Italy’s export value). Average tariff 2.9% until Jan 2025 → 15% from Apr 2025 .
- Estimated UIV impact : €317 million (up to €460 million with a weaker USD). Final markup from origination: estimated from 123% to 186% .
- Apr 2025 : Italy → USA –7.5% vol / –9.2% val . Jun 2025 : Italy €169.8 m (–4.2% m/m vs Jun ’24) ; France €191.3 million (5.9%) .
- Volume leadership confirmed: June 2025 Italy ~33 million liters (3.5%) = 32.6% of US imports; H1 2025 Italy 188.9 million liters (7.5%) > France (20.1% vol).
Focus Prosecco (UIV–Vinitaly / IWSR / SipSource)
- In the USA it is worth 31% of the value of Italian wine consumption ( $531 million in 2024 ).
- Awareness 40% (vs Champagne 52% ), but conversion to purchase 31% (Champagne 24% ).
- Sparkling wine share in the US (first 7 months of 2025): Prosecco 30% , Champagne 28% .
- Drivers: average price < $18 , strong penetration among women and Gen Z , use in mixology/RTD .
- Challenge: Growth in multi-ethnic communities (competitor: cocktails, hard seltzer, RTD).
Domestic demand and confidence (ISTAT, September 2025)
- Consumers : index from 96.2 → 96.8 ; economic climate 97.0 → 98.8 ; current 99.2 → 99.9 ; future 92.2 → 92.6 ; personal ≈96.0 .
- Businesses : 93.6 → 93.7 (stable); construction 101.3 → 101.5 , services 95.1 → 95.6 ; manufacturing stable 87.3 ; retail 102.7 → 101.6 .
- Wine implications: propensity for durable goods purchases slightly improved, but retail suffers; need to push by-the-glass , experiences, and entry-level pricing.
Ho.Re.Ca channel and distribution (Partesa interview)
- Excessive markups on entry-level labels are driving young people away.
- Virtuous model: wine by the glass with pouring technology, minimum quantities and continuity of supply, expansion of Italian labels.
- In 2025 price lists: avoid both drastic increases and decreases; focus on fresh whites and “pure” appellations with high quality/price ratios (Verdicchio, Garganega, Sangiovese, Chianti, Morellino).
Wine tourism and territorial branding
- International attraction for family-run wineries is growing: intention to visit on next trips → USA 78% , UK 74% , Germany 61% .
- Preference for family-run businesses : USA 68% , UK 57% , DE 49% ; very strong interest from Gen Z USA (82%) .
- Priorities: digital communication , multichannel promotion , AI to design experiences and manage flows. Key role: specialized consultant for omnichannel positioning and sales.
Policy, risks and operational proposals
- Safeguard Package (Eurispes): revision of Consolidated Law 238/2016 , yields/specifications/controls more in line with demand; labeling with ingredients and nutrition information ; simplification of inspections.
- Multi-level anti-counterfeiting : serial QR , RFID , NFC anti-tamper ; testing of new fiscal stamps started from 28 July 2025 .
- End-to-end AI : precision viticulture, winery (controlled fermentations, blends), marketing and CX.
- Plant authorizations : 1-year suspension of fines for non-use before January 2025; extension of replanting period to 8 years .
- Insurance/guarantees : evaluate an export coverage scheme similar to Cap Francexport; yield mutualization fund to stabilize prices (avoid sell-offs, dispose of surpluses, including through juice/distillation).
- US Tariffs : USWTA mobilizes industry with survey for economic evidence; leverage for negotiating pressure.
- Uprooting : German pan-European plan proposed (based on the 2009–2011 model); Italy more cautious → preference for reconversions and active vineyard management.
Opportunity to be seized immediately
- Rebalance export portfolio : boost Canada, Germany, Japan, and Brazil ; monitor the UK and China with targeted plans.
- Selective premium : communicating value (territory, sustainability, winemaking precision) to close the €-/l gap with the French.
- Prosecco : defend US share (mixology, RTD, non-Caucasian communities, West & East North Central).
- Family-friendly wine tourism : packages bookable online, transparent pricing, CRM and AI-driven UGC content.
- Ho.Re.Ca : inclusive price lists, by-the-glass , menus under €20–25 for quality entry-level options.
- Supply/Inventories : harvest-sales plans, cuvée segmentation, alternative channels for surpluses.
- Trust & Anti-Fake : Progressive rollout of QR-RFID-NFC new tags; storytelling on product security.
Final route note
2025 is the year for “active selection”: less product dispersion, more focus on markets and channels that boost margins and reputation, with Prosecco as the battering ram, wine tourism as the catalyst, and the digital/AI supply chain as the neural network. This is where the competitive advantage for the next 24 months will be built.
The Italian wine market continues to experience challenging times, with tariffs, falling prices, and new cultural and commercial challenges.
US exports: mixed signals
In the United States, Italy’s leading trading partner, July 2025 saw a significant decline in value of 21.1%. In the first seven months of the year, the overall figure was down 1.1% (€1.2 billion), although volumes grew (6.1%). The average price per liter fell to €5.48 (-6.8%), further compressing margins.
Sparkling wines are holding up better: up 4.3% in value (€357.3 million) and 14% in volume, but with prices falling to €4.63/liter (-8.5%). Bottled wines are struggling (-2.7% in value, but down 4.3% in volume), while bulk wines are plummeting (-39.5%).
France in the lead
In July, France surpassed Italy in exports to the US: €185.2 million versus €148.2 million. In the first seven months of 2025, French exports grew by 16.8% (€1.4 billion), with an average price nearly double that of Italy (€11.97/liter). Sparkling and bottled wines drove the performance, confirming their greater ability to hold up prices.
The cultural front: the appeal to the UN
The International Wine Academy has launched an appeal to world leaders to defend wine as a cultural, social, and human heritage, against the risk of it being reduced to a mere health threat. Among the signatories are prominent Italian winemakers such as Gaja, Zanella, Cinelli Colombini, and Lageder. The Academy emphasizes the value of moderate consumption, supported by recent scientific studies, and the need to preserve wine’s cultural identity.
New consumers in the US
The future of Italian wine also depends on renewing its target audience. UIV-Vinitaly and IWSR analyses indicate that the next American “wine lovers” will be primarily young people (Gen Z and Millennials), with a strong presence of Hispanic, African-American, and Asian consumers. States like Texas, California, Illinois, and Georgia thus become key markets for tapping into these new, high-potential communities.
Consortium strategies and the impact of tariffs
The sector is preparing for Vinitaly.USA (Chicago, October 5-6), a strategic event to gauge market reaction and defend Italy’s role in the United States. Consortia are facing a generous and high-quality harvest, but US tariffs—which rose to 15% on August 7—risk costing Italian companies up to €460 million. According to the UIV Wine Observatory, in the first three months of application, the duties have already generated an additional cost of $61 million and a 13.5% drop in import prices.
In short: Italian wine remains a leading player in the United States, but 2025 marks a crossroads: on the one hand, the challenge of prices and tariffs, on the other, the urgency of conquering new consumers and defending the cultural dimension of wine globally.
On the supply side, the 2025 harvest is estimated at 47–47.4 million hl with good/excellent quality and high cellar stocks (~37 million hl): a “precarious equilibrium” scenario in which protecting profitability is more important than maximizing volumes.
Global demand slowing, US tariffs at 15% compressing margins, Italian large-scale retail trade holding up in value but losing in volume.
Key points of the week
- Cavit (Trentino) : Message to suppliers — possible reductions in remuneration due to pressure on costs and profitability; declining international demand, US tariffs = ~$1 per shelf on wines priced at $14–$15. First half of 2025: -6–10% in various markets; sparkling wines 7.6% . Strategy: pass 10% on to consumers, 5% absorbed by the supply chain.
- Italian exports H1 2025 (Istat) : -0.4% value , -3.1% volume (~1 billion l). USA and Canada growing ; declines in Germany, UK, Russia, Asia (China, Japan) . Sparkling wines : value -0.4% (€1 billion), volume 0.1% (254.1 million l).
- Tre Bicchieri/Gambero Rosso : H1 2025 -0.48% value (€3.86 billion) ; volumes -3.2% . Prosecco Dop : volumes 3.9%, value 1.3% (€836 million) but lower mix ; Asti declines (quantity -16%, value -12%) in Russia. Bottles <2 l: values stable, volumes -3%.
- Large-scale retail trade in Italy (Circana) : last 12 months -0.7% value (€1.88 billion) , -2.5% volume (427.8 million litres) . Formats: 0.75 litre -0.9% (but 80% of the value, €1.4%), large bottles -7.7% , bricks -5.4% , bag-in-box 2.5% .
- US tariffs and prices : companies absorb the impact ; average price -13.5% in July (from $6.52 to $5.64/l). Tariff costs for Italy: $61 million in three months , just below France ($62.5 million).
- Regional export geography (H1 2025): Veneto leader €1.4 billion (1.5%, 37.1% of the total). Tuscany follows with €588 million (~-1%) , Piedmont with €553 million (-2.2%) . Lombardy (9.1%) , Friuli Venezia Giulia (15.2%) , Puglia (5.7%) , and Sicily (4.8%) are growing.
- China : Italy at €33.6 million (-21.7%) ; overall Chinese imports to restart in 2024, but sentiment with Italian wine remains weak ; the spotlight is on the Vinitaly China Roadshow .
- 2025 production : Italy expected to be #1 in the world (~ 47–47.4 million hl , 8% over 2024). Driven by the South (19%) ; Central Italy -3% (Tuscany -13%). Good/excellent quality, but risk of price pressure from high inventories.
- Climate & Policy : Supply chain divided over uprooting , yield reduction , plant permit management, and supply chain agreement (hypothesis of lower Ho.Re.Ca. markups versus rising restaurant costs). Convergence on extraordinary promotions (primarily in the USA) and on quality as a defensive lever.
Main markets (H1 2025)
- USA : €988 million (5.2%) , L179–180 million (1.1%) ; ongoing tariff impact, signs of slowdown in Q2 (Apr-Jun -1/-2%).
- Germany : €573 million (-1.8%) , 234.5 million l (-7.4%) .
- UK : €370 million (-4.5%) , €118 million (-2.1%) .
- Canada : €198 million (12.8%) , 34.9 million l (6.6%) .
- Switzerland : €195 million (0.4%) .
- France : €158 million (1.8/1.9%) .
- Russia : €75.6 million (-37.5%) , volumes halved; Prosecco -30% .
- Japan : €87–88 million (-7.4/7.5%) .
- China : €33.6 million (-21/22%) .
- Brazil : €18.6 million (5.5%) ; under special observation.
- Vietnam : €6.1 million (16%) .
Strategic reading (for wineries, consortia, investors)
- Profitability under pressure : tariffs, mix-downs, cost inflation and more moderate consumption are pushing us to reduce yields , reposition price lists and tighten promotional controls (avoiding “blind” discounts that erode brands).
- Portfolio shift : sparkling wines still resilient , but no longer the automatic locomotive; fresh whites and fast-moving denominations perform better than structured reds in large-scale retail outlets.
- Channels : Large-scale retail trade maintains value; bag-in-box growth: opportunities for “quality BIB” lines. On-trade must be revitalized with targeted policies and staff training.
- Geographies : The USA remains core but requires surgical pricing and anti-tariff plans (hedging, long-term contracts, co-promotions with distributors). Canada and Brazil are developing; Russia and China must be managed with selective tactics and B2B/B2C education projects. Northern EU is cooling: work on value/service .
- Supply : abundant harvest, high stocks ⇒ manage volumes (scheduled bulk sales, technical distillations where available, deferred bottling, selective private label only if it protects margins).
- Communication : telling the story of origin, sustainability, and conscious moderation ; less “extravagance,” more authenticity and accessibility .
Operational moves (next steps)
- US plans : simulate scenarios with 15% tariffs over 12 months; define absorption splits between supply chain and shelf; promotional contracts with anti-speculation clauses on pre-tax stocks.
- Mix & yields : for DOC/DOCG with price tension, evaluate a 10–20% yield cut and block excess spillovers on IGP where sustainable.
- Format portfolio : push premium 0.75L with perceived value; manage quality BIBs ; reduce unprofitable bottles/bricks.
- Market diversification : maintain US/Canada share; task force on Brazil/Vietnam ; B2B education projects in China (targeted roadshows, pairings with local Italian cuisine).
- Targeted Capex : Invest in cellar efficiency and commercial data analytics ; delay non-critical expenses.
- Supply chain agreement : collaboration with distribution and catering for sustainable markups and promotional scheduling; public-private co-branding campaigns.
TL;DR
Italy is #1 for 2025 production and high quality, but with full inventories and slower demand . US tariffs are compressing margins; large-scale retail trade is holding up in value, but volumes are declining ; Veneto is the export powerhouse. The key: protect margins with lower yields, a smart product mix, and targeted promotion in growing markets (USA, Canada, and Brazil), while the Chinese bet is rekindled with education projects.
The 2025 harvest promises to be one of the best in decades: an estimated 47.4 million hectoliters, 8% more than 2024.
Healthy grapes, excellent quality and peaks of excellence in many areas confirm Italy’s primacy in world production, ahead of France (37.4 million hl) and Spain (36.8 million hl).
The picture emerges from the joint survey by Assoenologi, Uiv, Ismea and Masaf , which returns a positive profile from a production point of view, but with important issues to be resolved on the consumption and market fronts.
A quality harvest, but a struggling market
Experts like Attilio Scienza emphasize the positive impact of the climate: the summer heat followed by August rains ensured optimal phenolic and aromatic ripening in almost all regions. Excellent signs were seen in Franciacorta, Oltrepò, Valpolicella, Prosecco, Friuli, and Marche; Tuscany saw a decline due to a deliberate decision to reduce yields.
But if production is smiling, high inventories, US duties, a wiped out Russian market, a drop in youth consumption and WHO campaigns are worrying.
Wine prices and value
“It’s absurd that a bottle of water costs €2.40 and a Chianti €3.60,” observes Riccardo Cotarella (Assoenologi) , calling for the urgent need to give greater value to the product . Lamberto Frescobaldi (UIV) also reiterates the need to reduce the quantities released on the market to preserve the value of Italian wine.
International markets: USA in crisis, Canada and Mexico on the rise
The US market is suffering severely: declining consumption, 15% tariffs, and new regulatory uncertainties. In response, Vinitaly is strengthening its presence with the wine2wine Business Forum (Chicago, October 5-6) and opening new routes to Canada, Mexico, and Central Asia . Opportunities are emerging from the Kazakhstan Roadshow , with over 475 operators involved and great interest in Italian wines.
Young people, sports and alcohol consumption
Surprising data comes from a study by the Liguria Local Health Authority (ASL3): young athletes consume 20-30% more alcohol than their sedentary peers. This phenomenon worsens with age, also linked to the presence of alcohol lobbyists in sports , and raises alarm about the future of responsible drinking.
Training and new wine professions
On the job market front, the Sant’Anna School of Advanced Studies in Pisa is launching the 11th edition of the Master’s Degree in Italian Wines and World Markets , a program of excellence that opens doors to roles in marketing, communications, export, and wine tourism. Approximately 70% of graduates find employment upon completion of their internship.
Final summary
In September 2025, Italian wine is experiencing a paradox: record-breaking quantity and quality, and struggling markets and consumption . The challenge will be to promote the product , contain yields, innovate communication for new generations, and find alternative international outlets . Italy remains the world leader, but the future will depend on the sector’s ability to transform this extraordinary harvest into a lasting competitive advantage.